
Government Bonds and UK Gilts
Government bonds are tradable loans. Starting with UK gilts, this video explains coupons, maturity, current yield and yield to maturity, then follows the same price–yield relationship through US Treasuries, Japanese Government Bonds and the separate sovereign issuers of the euro area.
Dated official evidence explains issuance, central-bank policy, inflation, demand and term premium. The 2022 LDI forced-sale episode is compared with the Bank of England’s 2026 market-function assessments. The final chapters trace borrowing costs to mortgages, businesses, pensions and government refinancing.
Examples are labelled hypothetical. Market observations retain their dates; policy rates are distinct from bond yields. Educational explanation, with no investment recommendation or crisis forecast.
Educational documentary. Not financial or investment advice.
Tags
Chapters
- Why a gilt headline matters
- A loan with a timetable
- The price–yield seesaw
- Short rates and long commitments
- Gilts: the UK starting point
- When repricing became dysfunction
- Treasuries: the global benchmark
- JGBs: Japan changes course
- Euro area: one policy, several issuers
- From markets to mortgages
- Pensions and the public purse
- Read the yield before the headline
Video notes
1. Why a gilt headline matters
A government borrowing headline can feel remote until a mortgage offer changes. The connection runs through markets where promises of future payments are bought and sold. Those markets help set the price of money over time. But a rising government yield does not, by itself, tell us that a crisis has begun.
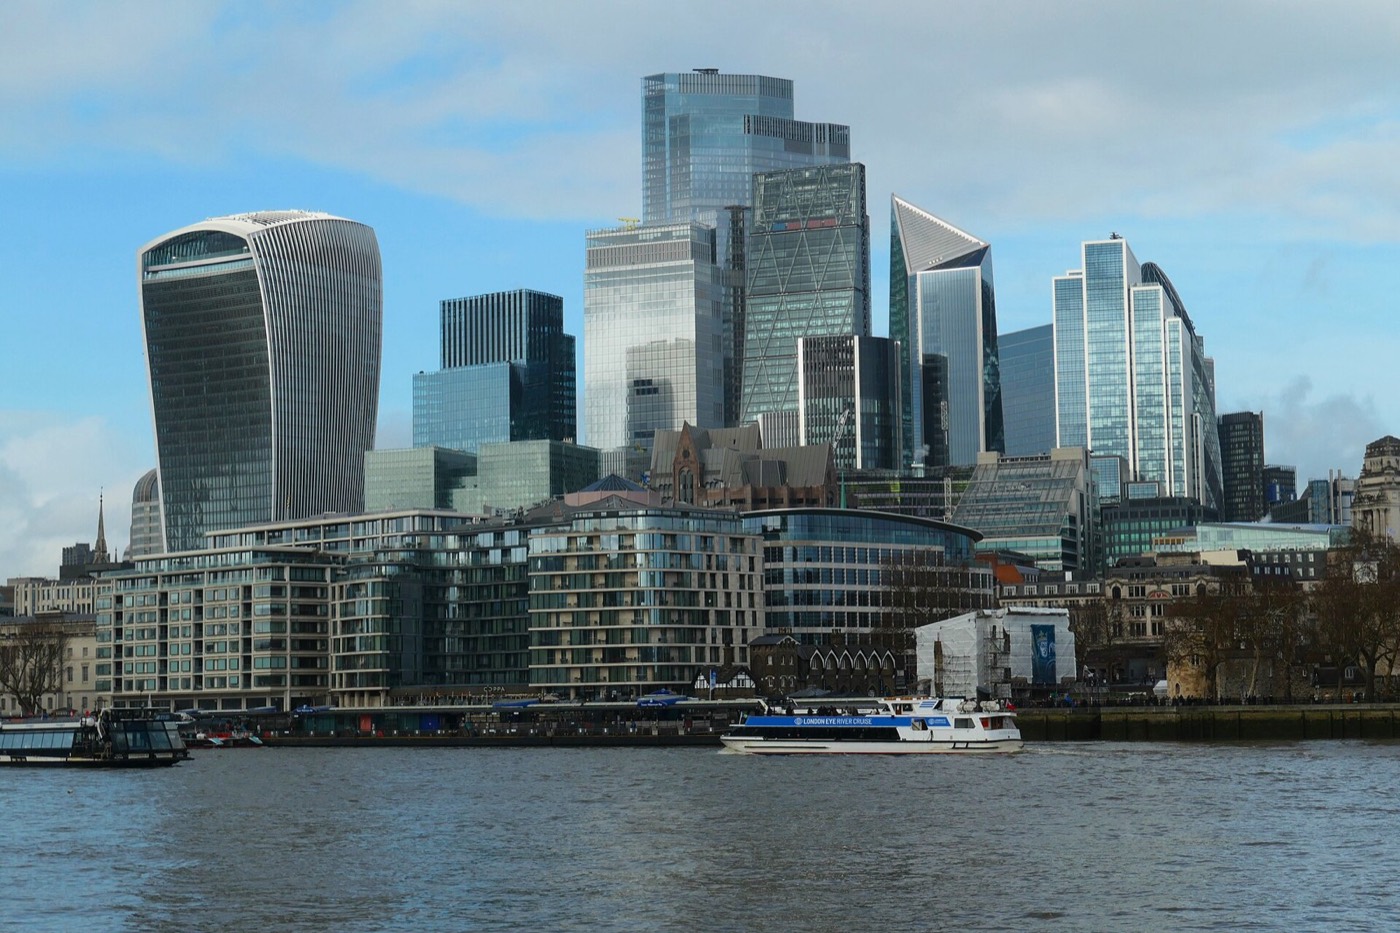
The City of London skyline sits beside the Thames. This contemporary view establishes the setting for the UK market, where government debt trades alongside the financial contracts used to price other borrowing.
A bond is a loan that can be traded. A government issues the promise, and the person holding it receives the promised payments. A gilt is the UK government's version, denominated in pounds. The name has an old association with security, but security of payment and stability of market price are different things.
A government bond connects public borrowing with private finance. Investors price the government's payment promise, while lenders use related market rates when pricing loans to households and businesses.
That connection has several moving parts. An overnight central-bank rate is different from a yield on debt stretching far into the future. A mortgage rate also includes the lender's own costs and risks. We need to understand the bond first, then follow the links outward.
A yield headline needs a maturity and an observation date. It also needs a currency and a check on whether trading is functioning normally. Without that context, a precise percentage can still tell an incomplete story.
We will start with gilts, then compare America, Japan and the euro area. The same basic arithmetic runs through all of them. The institutions, currencies and buyers make their stories different. This video explains those differences without predicting a crisis or recommending an investment.
London is our UK starting point, with New York representing dollar finance and Tokyo representing Japan. Germany, France and Italy provide the euro-area comparison. This map locates the markets, rather than measuring trade or capital flows.
2. A loan with a timetable
The promise begins with an issuer, the borrower legally responsible for paying. For a conventional gilt, that borrower is the UK government. Its payments are fixed in pounds, with a timetable that remains in place even when the bond changes hands.
The Palace of Westminster is a setting for the government behind that promise. This contemporary exterior is a place reference, rather than a picture of a bond transaction or an announcement being made.
Face value means the amount due back at the end. The coupon is the regular interest payment. Maturity is the date the loan ends. These terms describe the promise itself, rather than the price somebody happens to pay for it today.
Imagine a gilt with a hundred pounds of face value and a four per cent coupon. It pays four pounds a year, divided into two payments. At maturity, the holder receives the face value back, alongside the final interest payment. These are hypothetical terms.
The government's Debt Management Office, or DMO, arranges gilt issuance. Issuance means selling newly created debt to raise money. The amount raised can differ from the face value because the price paid may be above or below it. Quoted prices also need care over interest accumulated between payment dates.
At issue, an investor's money goes towards government financing. On resale, the buyer pays the existing holder instead. The government still owes the scheduled payments, but that resale does not itself provide new cash to the government.
Trading matters because holders do not all want to wait until maturity. Some need cash, while others want a different maturity or risk exposure. A sale transfers the payment promise to another holder. The market price is what makes that transfer possible, and it is free to move.
3. The price–yield seesaw
Keep the payment promise fixed and change only the price. This is the simplest way into the bond market. The coupon belongs to the terms of the bond. The yield belongs to the relationship between those terms and the price paid.
Our hypothetical bond still pays four pounds each year. At an eighty-pound price, its current yield is five per cent. At a hundred and twenty pounds, the current yield is about three point three three per cent. The same cash payment buys a different return on the purchase price.
Current yield divides annual interest by the market price. It leaves out the gain or loss between that price and the amount returned at maturity. Buying below face value adds a possible capital gain if the promise is honoured. Buying above face value brings the opposite effect at redemption.
Yield to maturity includes the scheduled interest and the final repayment. It is the discount rate that makes those future payments equal today's price. It is different from current yield because it accounts for the full timetable.
That calculation describes a promised return under its assumptions. It does not remove default risk, tax, trading costs or the risk of selling early. The usual return interpretation also assumes coupon payments can be reinvested at that yield. An actual holder's experience can differ.
With unchanged promised cash flows, price down means yield to maturity up. Price up means yield down. The bond's coupon does not reset when its market price changes.
This is why a report of higher yields is also a report of lower prices for existing fixed-payment bonds. It is the same event viewed from different sides. A saver buying today and a holder selling today experience that change differently, even though they meet at the same market price.
4. Short rates and long commitments
A central bank influences the overnight price of money. A long bond commits money across many future policy decisions. Its yield therefore reflects expectations about future short rates, alongside compensation for holding a longer and less certain commitment.
Bank Rate was held at three point seven five per cent in September twenty twenty-six. That is the Bank of England's policy rate. It is not the yield on a long gilt, and it does not fix that yield directly.
Inflation means money buys less over time. Expected inflation matters to a bond whose payments stay fixed in cash. It can affect expectations of central-bank policy and the compensation investors demand for uncertainty. Stronger growth, weaker growth and changes in government financing can also alter the calculation.
Long yields respond to policy expectations, inflation, issuance and investor demand. The term premium is the estimated extra return for bearing a long commitment rather than repeatedly lending short. These influences interact, rather than operating as separate switches.
The split is estimated because we cannot directly observe the market's complete future policy path. Different models can produce different answers. Nor is the term premium automatically positive: some investors value long bonds as protection against other risks. Their demand can make that estimated premium negative.
Duration measures how sensitive a bond's price is to changes in yield. Payments further away generally make a fixed-payment bond more sensitive. A longer wait can therefore produce a larger price movement for the same yield change, other things equal.
More issuance means more debt for buyers to absorb, but quantity alone does not decide the yield. A change in demand can offset it. Central-bank buying or selling can influence those conditions too. The long rate is a market outcome, shaped by the future people expect and the risks they will carry.
5. Gilts: the UK starting point
The UK finances new borrowing and replaces debt reaching maturity through a programme of issuance. The DMO publishes calendars so participants can prepare. Predictability helps, but investors still decide what price they will pay for each payment timetable.
The DMO planned twelve gilt auctions for October to December twenty twenty-six. The calendar was published in late August. These are planned operations, rather than a promise that every bond will be sold at a particular yield.
One actual long-dated sale gives us a concrete example. On the eighth of September, the DMO priced a re-opening of a gilt maturing in twenty fifty-six. A re-opening adds more debt with the same terms as an existing gilt. It helps build a larger tradable issue.
The sale covered four point two five billion pounds of face value. Its coupon was five point three seven five per cent. The price was ninety-three point eight zero six pounds per hundred pounds of face value. Its gross redemption yield was five point eight one six eight per cent.
Those figures describe that transaction, not today's generic long-gilt yield. Price, coupon and redemption yield are separate quantities. The coupon was lower than the yield because buyers paid below face value for the promised payments. The maturity date matters to that calculation as well.
Conventional gilts promise fixed cash payments. Index-linked gilts adjust payments with the Retail Prices Index, using a lag. They change the inflation exposure, but their market prices can still fall when the yields investors require rise.
Pension funds have been important buyers of long gilts because their payments to members stretch into the future. Their demand can change as schemes mature or alter their hedging. The Bank's September minutes identified reduced long-term demand alongside global uncertainty and high issuance as influences on long-term risk compensation.
6. When repricing became dysfunction
A market can move sharply and still allow buyers and sellers to trade. Dysfunction begins when the plumbing cannot cope. In the UK's pension-related stress, falling bond prices interacted with urgent demands for cash and collateral, creating pressure beyond an ordinary reassessment of value.
In September twenty twenty-two, gilt yields rose sharply after the government's fiscal announcement. The Bank of England began temporary purchases on the twenty-eighth of September. Those purchases ended on the fourteenth of October. The intervention bought time for funds to reduce their vulnerability.
Liability-driven investment, or LDI, means arranging investments to match a pension scheme's future payment obligations. Some strategies used borrowing and financial contracts to increase their exposure. That leverage meant a comparatively small amount of available cash supported a larger position.
Rising yields lowered the value of the bonds supporting those positions. Collateral calls demanded extra cash or assets to secure the contracts. Funds sold gilts to meet the calls, pushing prices down further and generating still more pressure to sell.
The Bank bought nineteen point three billion pounds of gilts during the intervention. Its later account describes purchases aimed at restoring market functioning. This was a response to a forced-sale mechanism, rather than a statement that any particular long yield was inherently unacceptable.
The Bank's July twenty twenty-six assessment described sizeable gilt moves without notable disruption. The comparison is between stressed trading and orderly repricing. That dated assessment does not guarantee that future shocks will be absorbed equally well.
The September minutes also described orderly functioning over the preceding year. That is useful newer evidence, but vigilance remains necessary. Liquidity means the ability to trade without moving the price excessively. Borrowing, concentrated positions and dealers' capacity to handle sales can all affect it. A yield level alone cannot diagnose those conditions.
7. Treasuries: the global benchmark
The United States borrows through marketable Treasury securities, meaning securities holders can sell. The family includes several payment structures. They share an issuer, but they do not all offer the same maturity or protection against inflation.
Treasury bills are short-term debt without a regular coupon. Notes pay interest and cover intermediate maturities. Bonds extend further into the future. Treasury inflation-protected securities, called TIPS, adjust their principal with American consumer-price inflation.
Treasury notes are issued at two and three years. Other note maturities are five, seven and ten years. Treasury bonds are issued at twenty and thirty years. Floating-rate notes are another category, with interest payments that change under their stated terms. The label tells us which promise we are discussing.
This contemporary New York Financial District exterior places us near the businesses trading dollar finance. It is a location photograph, rather than evidence of a particular market move or a particular trader's decision.
Treasuries influence prices well beyond the government's own borrowing. They are widely used as collateral, meaning assets pledged to secure a loan or transaction. Dollar loans and other securities are often priced relative to Treasury rates. The benchmark is a starting point, with other risks added around it.
On the second of October twenty twenty-six, the Treasury's two-year par yield was four point eight three per cent. The ten-year figure was five point two eight per cent. At thirty years, it was five point six three per cent. These are interpolated par yields, not coupons on three individual bonds.
A par yield describes the coupon that would price a hypothetical bond at face value on the fitted curve. The curve joins yields across maturities. Its shape reflects Federal Reserve policy expectations, issuance, demand and risk compensation. Overseas demand matters too, but changes in currency values and hedging costs affect what a foreign buyer actually receives.
London, New York and Tokyo are connected through investors operating across currencies. A change in dollar bond pricing can affect financial conditions elsewhere. These links transmit incentives and risks, rather than making every national yield move by the same amount.
8. JGBs: Japan changes course
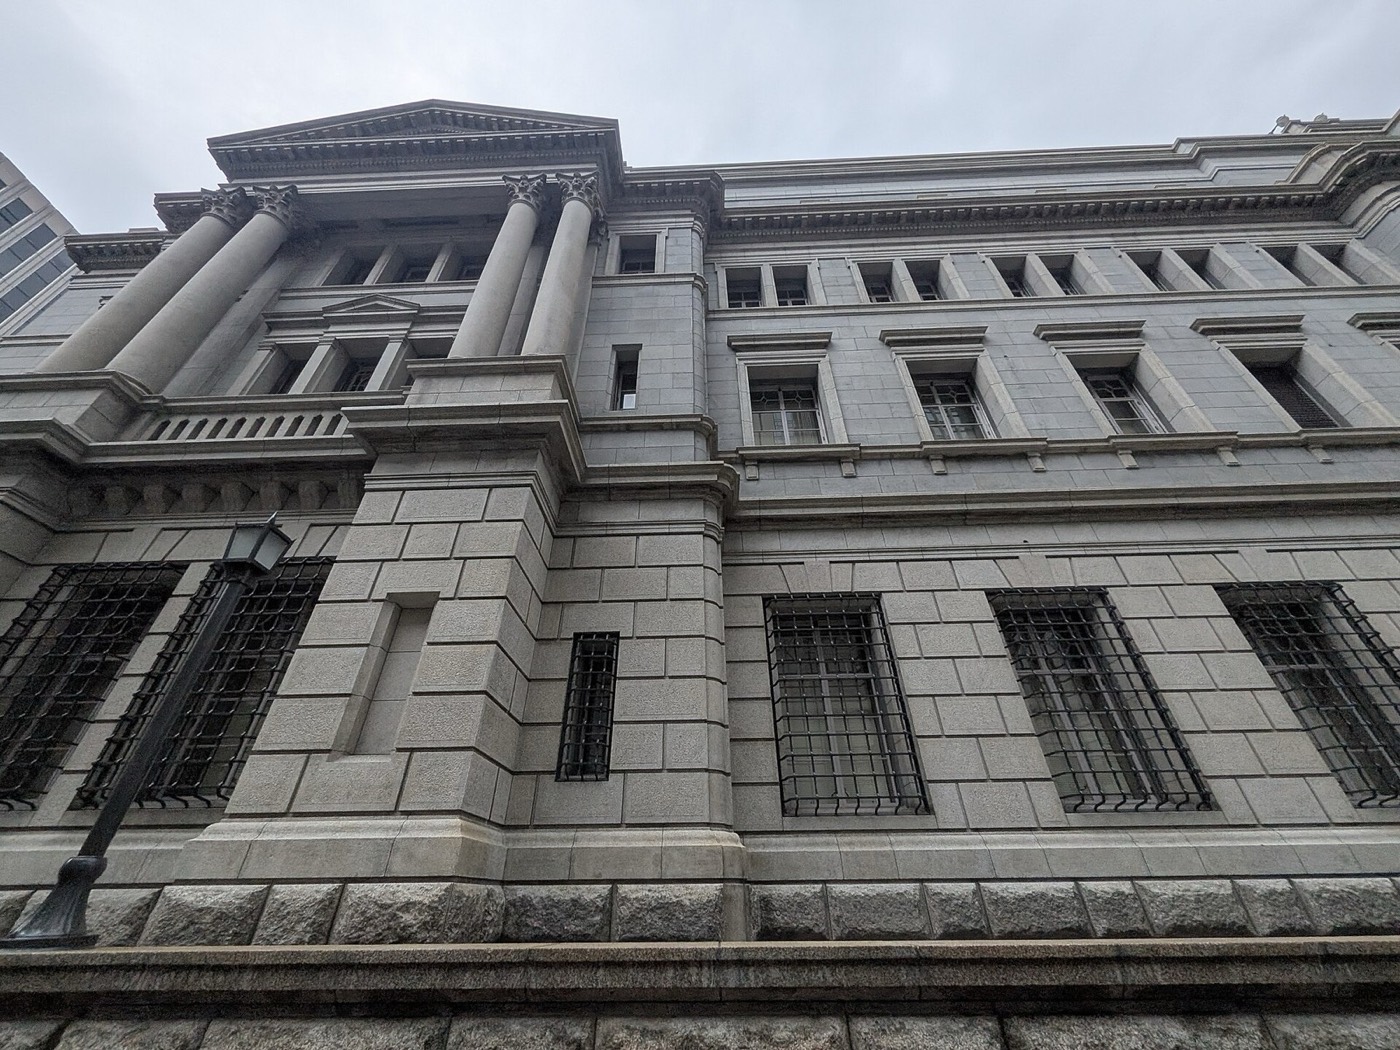
Japanese Government Bonds, or JGBs, are Japan's sovereign debt. For years, low inflation and strong central-bank support helped shape a very different interest-rate environment. Moving away from that setting changes the balance between policy support and the prices formed by private buyers.
The Bank of Japan head office stands in Tokyo. This contemporary exterior identifies the institution whose policy decisions and bond purchases influence the yen market. It does not depict a meeting or a policy announcement.
Tokyo sits at the centre of Japan's bond-policy story, while London and New York represent connected overseas markets. Investors can compare opportunities across these places. Currency changes and hedging costs mean those comparisons require more than a yield number.
In March twenty twenty-four, Japan ended negative interest rates and yield curve control. Yield curve control meant targeting the yield on a selected bond maturity through policy operations. In September twenty twenty-six, the overnight call-rate guideline became around one point two five per cent.
The overnight call rate is a short-term interbank lending rate, rather than a long JGB yield. Ending the old framework did not mean stopping every purchase immediately. The Bank continued buying bonds while setting out a gradual reduction. That changes demand over time and gives private investors a larger role in price formation.
The June purchase plan set monthly buying near two point three trillion yen for October to December twenty twenty-six. It then planned about two point one trillion for the following quarter. From April twenty twenty-seven, the planned monthly amount was about two trillion yen, with flexibility if markets came under stress.
The plan is a path for purchases, not a forecast of bond yields. Higher yields can increase the cost of new debt and refinancing. The effect on total government interest payments arrives gradually because old fixed-rate debt retains its terms until it is replaced.
Japan's finance ministry showed estimated general-government gross debt at two hundred and thirty per cent of GDP for twenty twenty-five. GDP measures the economy's annual output. This broad debt measure includes central and local government and social-security funds; it is not net debt after financial assets.
Borrowing in the government's own currency reduces some funding risks. It does not remove inflation risk or the budget consequences of higher interest costs. Rising domestic yields can also change the appeal of overseas bonds for Japanese investors. Exchange rates and the cost of hedging those currencies complicate the comparison, so a wholesale return of money is a possible channel, not a prediction.
9. Euro area: one policy, several issuers
The euro area shares a currency and central-bank policy. It still contains separate governments with separate debts. A common policy rate therefore does not create a single price for every government's long-term borrowing.
Germany issues Bunds, France issues OATs, and Italy issues BTPs. The European Central Bank sets monetary policy for the euro area. The UK sits outside that shared currency, so gilts belong to a separate monetary system.
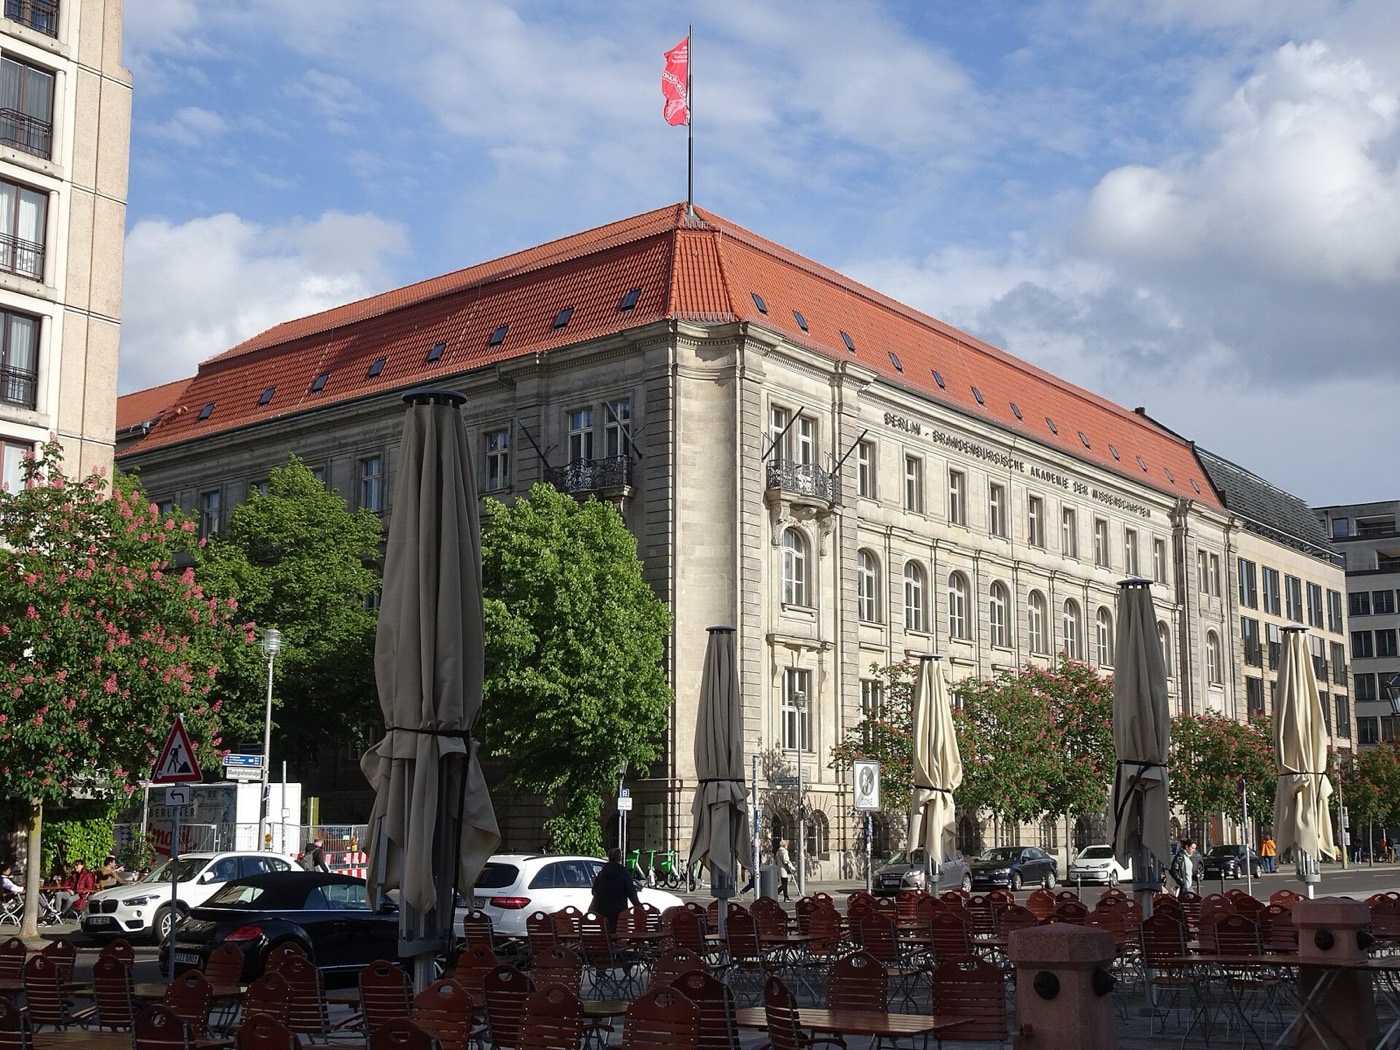
This central Berlin exterior locates the German part of the comparison. It is a contemporary city reference, not the debt-management office itself. A Bund is a promise of the German federal government.
OAT is the French name for a Treasury bond category. BTP is the conventional Italian Treasury bond, with fixed half-yearly interest. The names identify national issuers, even though their payments use the same currency.
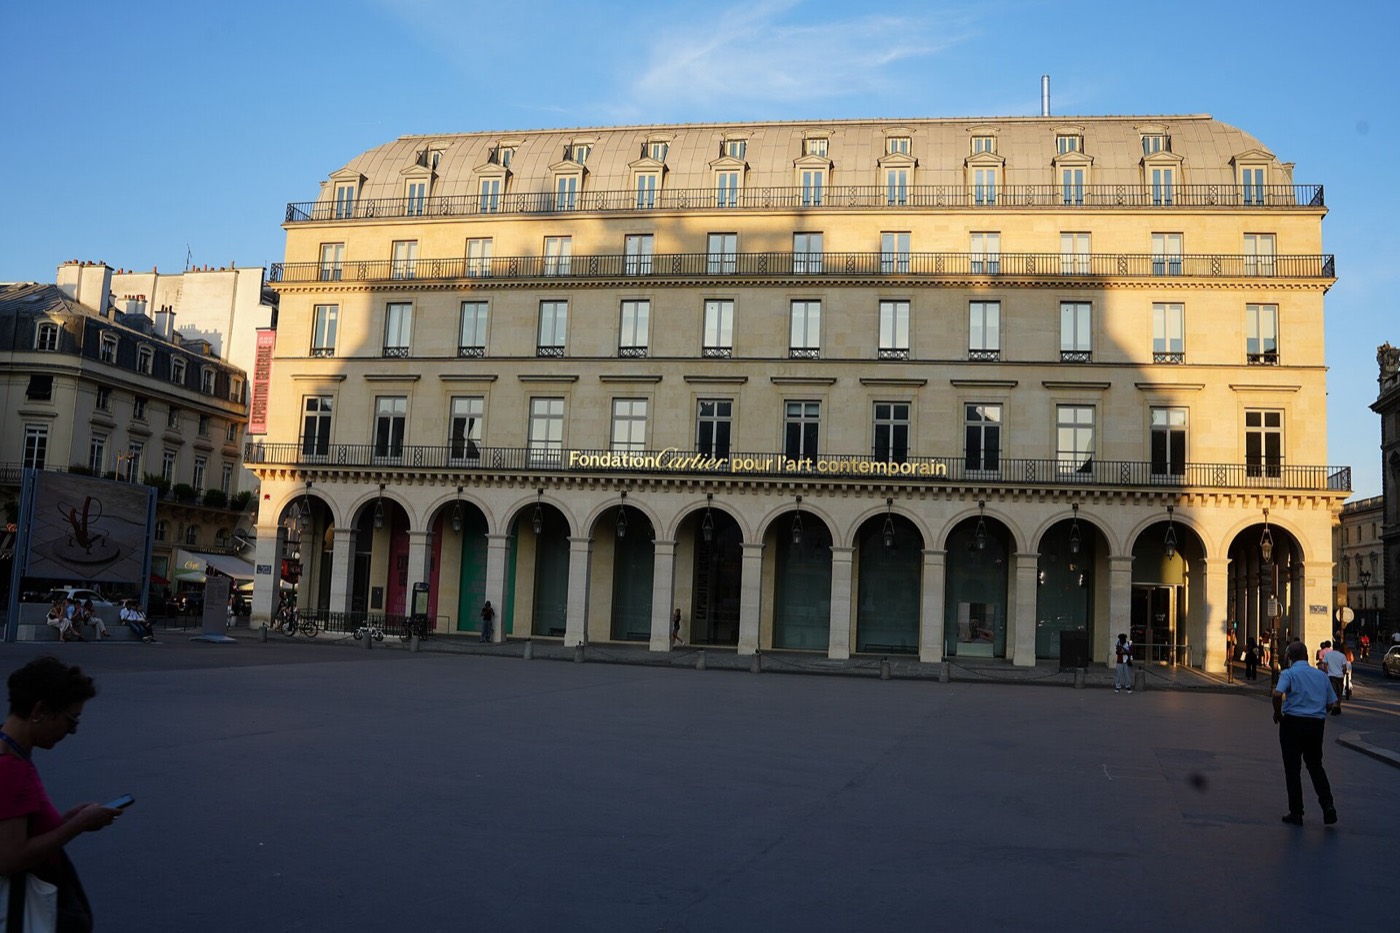
This Paris exterior near the Louvre is an illustrative city background. It establishes the French setting without pretending to show an auction. France's bond payments depend on the French issuer's commitments.
The ECB raised its deposit rate to two point five zero per cent, effective in September twenty twenty-six. This is a shared policy rate. National yields also reflect fiscal prospects, credit risk, liquidity and political uncertainty.
The European Central Bank's tower in Frankfurt identifies that shared policy institution. Its decisions influence financing across the currency area. They do not erase the separate responsibilities of national treasuries.
Imagine an Italian yield of four per cent and a German yield of three per cent at the same maturity. The gap is one percentage point, or a hundred basis points. This hypothetical spread compares sovereign borrowing rates; it is not a live market quote.
The buildings along Via San Teodoro place the Italian part of the story in Rome. This contemporary view is an illustrative setting. It is not evidence of stress in the Italian bond market.
The ECB publishes yield curves for groups of government issuers. One uses highly rated issuers, while another includes all euro-area central governments. Neither aggregate is the borrowing curve of a single nation.
A spread needs the same maturity and observation date to be meaningful. It also needs a clearly stated comparison bond. EU borrowing adds a separate issuer; it does not replace these national markets. The shared currency removes currency differences within this comparison, while leaving differences in the promises and the markets trading them.
10. From markets to mortgages
Government yields reach ordinary borrowers through several channels. They influence the alternatives available to savers and lenders. They also move alongside contracts that lenders use to manage interest-rate exposure. The result is a connection, but never a universal formula linking a gilt percentage to a mortgage offer.
Northway House in Whetstone is an illustrative view of UK housing. Borrowers living in homes like these can face changing finance costs when arranging or renewing a loan. The photograph does not identify the borrowing circumstances of its residents.
A swap is a contract exchanging one stream of interest payments for another. An overnight index swap, or OIS, links payments to an overnight rate over an agreed period. Its pricing helps show market expectations and risk compensation over that period. Lenders use such markets when managing fixed-rate lending.
Expected policy rates feed into swap pricing and lenders' funding costs. A mortgage offer also includes credit risk, operating costs and the lender's margin. Competition and the borrower's circumstances affect the final quote.
A credit spread is the extra interest required above a reference rate for additional lending risk. A business can face a higher reference rate, a wider spread, or both. That can change whether a new workshop, machine or expansion pays for itself. Government bond markets are therefore relevant beyond public finance.
The Bank's September twenty twenty-six minutes reported two-year fixed mortgage quotes around ninety-five basis points above pre-conflict levels. That is roughly zero point nine five percentage points. The minutes linked lending-rate increases to short-term OIS rates, rather than a one-for-one change in long-gilt yields.
An existing fixed-rate mortgage normally keeps its agreed rate during the fixed period. The pressure appears when that period ends or a new loan is arranged. Other contracts can adjust sooner. This uneven timing helps explain why market news can arrive immediately while its effect on household spending builds over months.
11. Pensions and the public purse
A pension scheme has assets and promises. Bonds can be among its assets. The promises are future payments to members, which must be valued today. Looking only at the bond portfolio can therefore miss what is happening on the other side of the balance sheet.
A higher discount rate reduces the present value of a future payment. It can lower the measured value of pension liabilities at the same time as bond asset prices fall. Whether funding improves depends on the match between the assets and those promises.
Discounting means translating future payments into an equivalent value now, using an interest rate. It changes the valuation, rather than cancelling the pension payments themselves. Hedging means arranging positions to offset a risk. How much a scheme hedges determines how closely its assets move with its measured obligations.
Pension funding and pension liquidity answer different questions. Funding compares assets with obligations. Liquidity asks whether cash or suitable collateral is available when needed. A scheme can improve on the first measure while still struggling with an urgent collateral call.
The public purse has its own timing problem. A higher market yield does not rewrite the coupon on every outstanding conventional gilt. It affects the price of borrowing now. The government gradually encounters that price as it issues new debt and replaces debt reaching maturity.
Old fixed coupons continue under their original terms. Refinancing means borrowing again to repay maturing debt, and the new borrowing carries the new market cost. Index-linked debt adds a separate channel because its payments adjust with the inflation measure specified in the bond.
That gradual transmission matters when interpreting estimates of future interest spending. A calculation needs the debt's maturity pattern and composition, alongside assumptions about rates and inflation. Today's yield cannot simply be multiplied by the whole debt stock and called today's bill. Neither a household nor a government renews every loan at once.
12. Read the yield before the headline
Return to the headline that started the story. A yield has moved. We now know that the first task is identifying which promise has been repriced. The second is understanding the market around it. The third is following how that change reaches other borrowing.
Gilts are UK debt in pounds; Treasuries are American debt in dollars. JGBs are Japanese debt in yen. Bunds, OATs and BTPs are separate national debts using the euro. Each market combines payment promises with its own policy and investor setting.
The same price–yield relationship helps interpret all four. Fixed payments become more or less attractive as prices change. But a foreign-currency yield is not automatically the return available in a household's home currency. Exchange rates and hedging can change that outcome.
Read the maturity, currency and observation date beside the yield. Check whether the figure is a bond's redemption yield, a fitted curve rate or a central-bank policy rate. Those labels tell us whether two numbers can fairly be compared.
Then ask what might explain the movement. Policy expectations are one candidate. Inflation, issuance, demand and risk compensation are others. A sharp move can be consequential without being evidence that buyers and sellers have lost the ability to trade.
Repricing changes the terms on which money is available. Dysfunction adds a failure in trading or funding, such as a forced-sale spiral. A crisis diagnosis needs evidence about those mechanisms, rather than a yield threshold standing alone.
Higher borrowing costs can squeeze households, businesses and government budgets. They can also change pension valuations on both sides of the balance sheet. Understanding the timetable prevents an instant market move from being mistaken for an instant change in every payment. That is the useful lesson of the bond market: read the promise, read the price, and then trace the consequences.
Sources and credits
Photo credits (Wikimedia Commons)
- City of London skyline across the Thames — 30 January 2026: jacquemart, CC0 - https://commons.wikimedia.org/wiki/File%3AThe_City_of_London_2026-01-30.jpg
- Palace of Westminster exterior — 17 May 2026: Aethonatic, CC0 - https://commons.wikimedia.org/wiki/File%3APalace_of_Westminster_-_17_May_2026.jpg
- Bank of Japan Head Office, Nihonbashi, Tokyo — 16 August 2026: Syced, CC0 - https://commons.wikimedia.org/wiki/File%3ABank_of_Japan_building_%2897648%29.jpg
- Central Berlin: Berlin-Brandenburg Academy exterior from Gendarmenmarkt — 13 May 2026 per Commons capture metadata: Ixicon, CC0 - https://commons.wikimedia.org/wiki/File%3ABBAW-berlin-geb%C3%A4ude-vom-gendarmenmarkt-ecke-jaegerstr-2026-05-26.jpg
- European Central Bank Skytower, Frankfurt, west exterior — 11 April 2026: Karlunun, CC0 - https://commons.wikimedia.org/wiki/File%3AFfM_Ezb_Skytower_W_85_IMG_20260411_1425.jpg
- New York Financial District: 1 William Street exterior — 25 August 2026: Station1, CC0 - https://commons.wikimedia.org/wiki/File%3AOneWilliamStAug2026.jpg
- Rome: buildings along Via San Teodoro viewed from the Roman Forum — 7 June 2026: Julian Lupyan, CC0 - https://commons.wikimedia.org/wiki/File%3ABuildings_along_Via_San_Teodoro%2C_Viewed_from_the_Roman_Forum%2C_Rome%2C_Italy.jpg
- UK homes: Northway House residential building, Whetstone, London — 8 March 2026; illustrative housing exterior: Mike Lidgley, CC0 - https://commons.wikimedia.org/wiki/File%3A1379_Finchley_High_Road_-_Northway_House%2C_Whetstone%2C_London_N20.jpg
- Paris: building exterior near the Louvre, 1st arrondissement — 24 July 2026; illustrative city background: Adoscam, CC0 - https://commons.wikimedia.org/wiki/File%3AWikimania_2026_%E2%80%93_Sortie_photographique_autour_du_Louvre%2C_1er_arrondissement_de_Paris_03.jpg


Not regulated financial advice.