
Property: prices, rents, supply, demand and mortgage rates
Why does the same home have a sale price and a rent, and why do they move differently? This video explains housing supply, household formation, employment, wages, deposits, mortgage credit and confidence.
Follow higher rates through mortgage payments, buyer budgets and weaker funded demand. Then calculate Joe’s illustrative 5% gross rental yield and distinguish it from operating yield, financed cash flow and total return. Landlord costs, tenant affordability, England’s dated rent rules and property risks complete the explanation.
Observed figures are dated; calculations are illustrations. No price forecast or investment recommendation. Sources and calculations are documented in the fact sheet.
Educational documentary. Not financial or investment advice.
Tags
Chapters
Video notes
1. One home, two markets
A house can carry two prices at once. There is the amount someone will pay to own it, and the amount someone will pay to live in it for a while. Those prices are connected. They are not the same market, and they do not have to move together.
The sale price buys ownership. The rent buys the use of a home over time. A buyer needs savings and often a loan; a tenant needs enough income to meet the rent. Start by keeping those decisions apart.
Joe’s example is a property worth three hundred thousand pounds. It earns fifteen thousand pounds in annual rent. Later we will divide one by the other, but first we need to understand what can change each side of that calculation.
The Office for National Statistics reports UK annual private rent growth of three point eight per cent to August twenty twenty-six. House price growth was one point four per cent to July. Both figures are provisional, and their end months differ. These are changes from a year earlier, not forecasts.
That snapshot was released on the sixteenth of September. The rent measure covers new and existing tenancies, rather than only asking rents on property websites. A national average also cannot tell you what a particular street will do. The condition and location of an individual home still matter.
There is a newer lender snapshot too. Nationwide’s release on the first of October reports annual house price growth of zero point eight per cent in September. Its mortgage-based index is a different measure from the ONS index. Keep the source attached to the number.
Slower growth still means growth when the rate remains positive. It does not mean the price level has fallen by that percentage. Through this video we will separate levels from changes, observed data from examples, and a landlord’s rent receipts from the money actually left over.
2. Why housing cycles repeat
People can become very confident about property because the object seems permanent. A wall stays where it is. A mortgage valuation does not. The same building can command a different price when buyers have different incomes, different expectations or different access to loans.
The Bank of England’s historical account starts with UK prices doubling between nineteen eighty-four and nineteen eighty-nine. Falling prices then continued for more than five years. The earlier price level was not regained until nineteen ninety-nine. These are cash prices, before adjusting for inflation.
The distinction matters. If the pounds required to buy a house return to an old level, those pounds may buy fewer other things than before. A recovery in the cash price is not necessarily a recovery in purchasing power. Nor does it reimburse every owner for interest and selling costs.
A price rise can encourage buyers to expect another rise. That expectation can bring more bidding, which reinforces the first rise. The loop can reverse when borrowing becomes harder or confidence weakens. The building has not changed, but the bidding has.
The rate shock of twenty twenty-two provides a more recent reminder. Borrowing costs rose, and mortgage deals changed quickly. A buyer who could meet yesterday’s payment might struggle with today’s offer. This is a credit shock reaching the housing market, rather than a sudden disappearance of the need for homes.
Put twenty twenty-two beside the earlier cycle as a reminder of risk, not a timetable for the next crash. More expensive borrowing can weaken budgets. It does not tell us exactly when every local price will turn.
Cycles do not repeat with identical causes or identical outcomes. Fixed mortgage deals, household savings, employment and the number of homes for sale all affect the adjustment. History establishes that prices can fall. It does not supply a guaranteed pattern that a buyer can trade against.
3. Who wants a home?
Housing demand starts with people arranging their lives. An adult leaves the family home. A couple separates. Someone moves for work. People arrive from another country, while others leave. The important question is how those changes translate into households seeking homes in particular places.
Population and household formation are different things. More people can share an existing home, while the same population can form more separate households. Either migration or changes in living arrangements can alter the pressure on housing. The effect depends on where those households settle.
A home near suitable work may be useful in a way an empty home far away is not. Transport, schools and family connections can matter too. That is why a national count of buildings cannot settle every local shortage. The homes and the people have to match in place and suitability.
Housing need is the need for somewhere suitable to live. Funded demand is the ability to pay the price being asked. A household can have an urgent need while lacking the savings or income to buy. Need does not automatically become a successful bid.
Jobs and wages connect the two. Secure earnings help someone pay rent, save a deposit and qualify for a mortgage. Losing work can weaken all three. A lender’s decision matters alongside the household’s own calculation, because willingness to borrow does not guarantee permission to borrow.
Investors also bid for homes. They compare expected rent and possible resale proceeds with borrowing costs and other expenses. An investor can compete with an owner-occupier for the same property. A change in the investor’s calculation can therefore change the pool of buyers.
Buying an existing rental does not itself create an extra building. Converting a building or financing construction may do so. Keep the transaction and the physical addition separate. Demand explains who wants to compete; supply explains what they can compete for. Neither side is enough on its own.
4. Why supply takes years
Imagine a town suddenly gaining jobs. People can start searching for homes immediately. The town cannot immediately produce a finished neighbourhood. New housing passes through decisions and physical work, with different delays at different sites. There is no single build time that describes every development.
Land must be available, and permission must allow the proposed homes. Roads, drainage and utilities must support them. Construction then needs materials, workers and finance. These are linked stages, and a problem at one stage can hold up completion.
Higher sale prices can make a project more attractive, but higher building costs can work in the other direction. Scarce skilled labour may delay work or raise costs. A permission is not a finished home. A completed home also has to be somewhere people can use it.
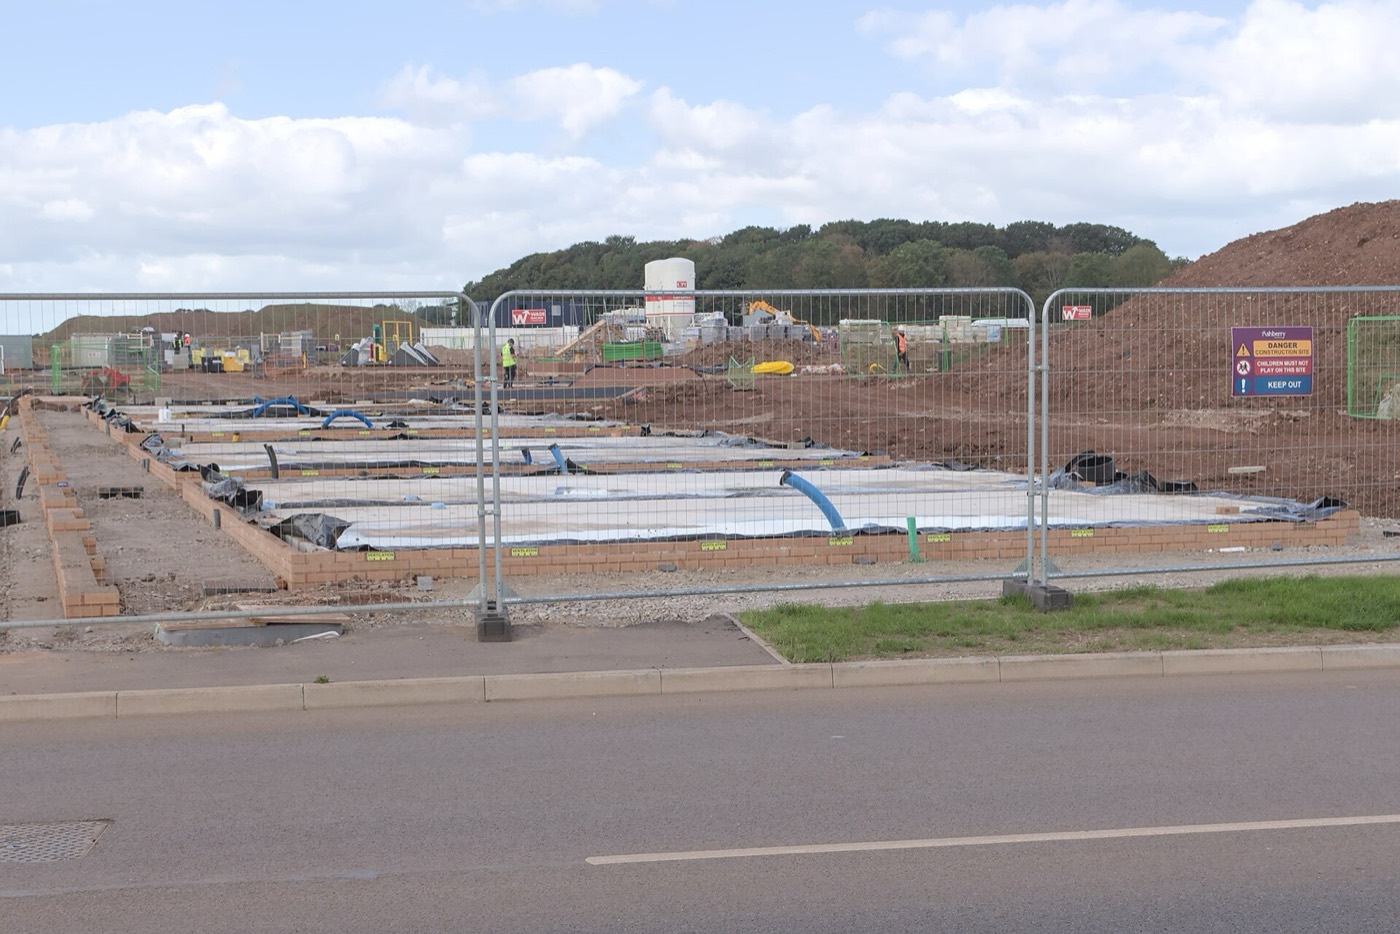
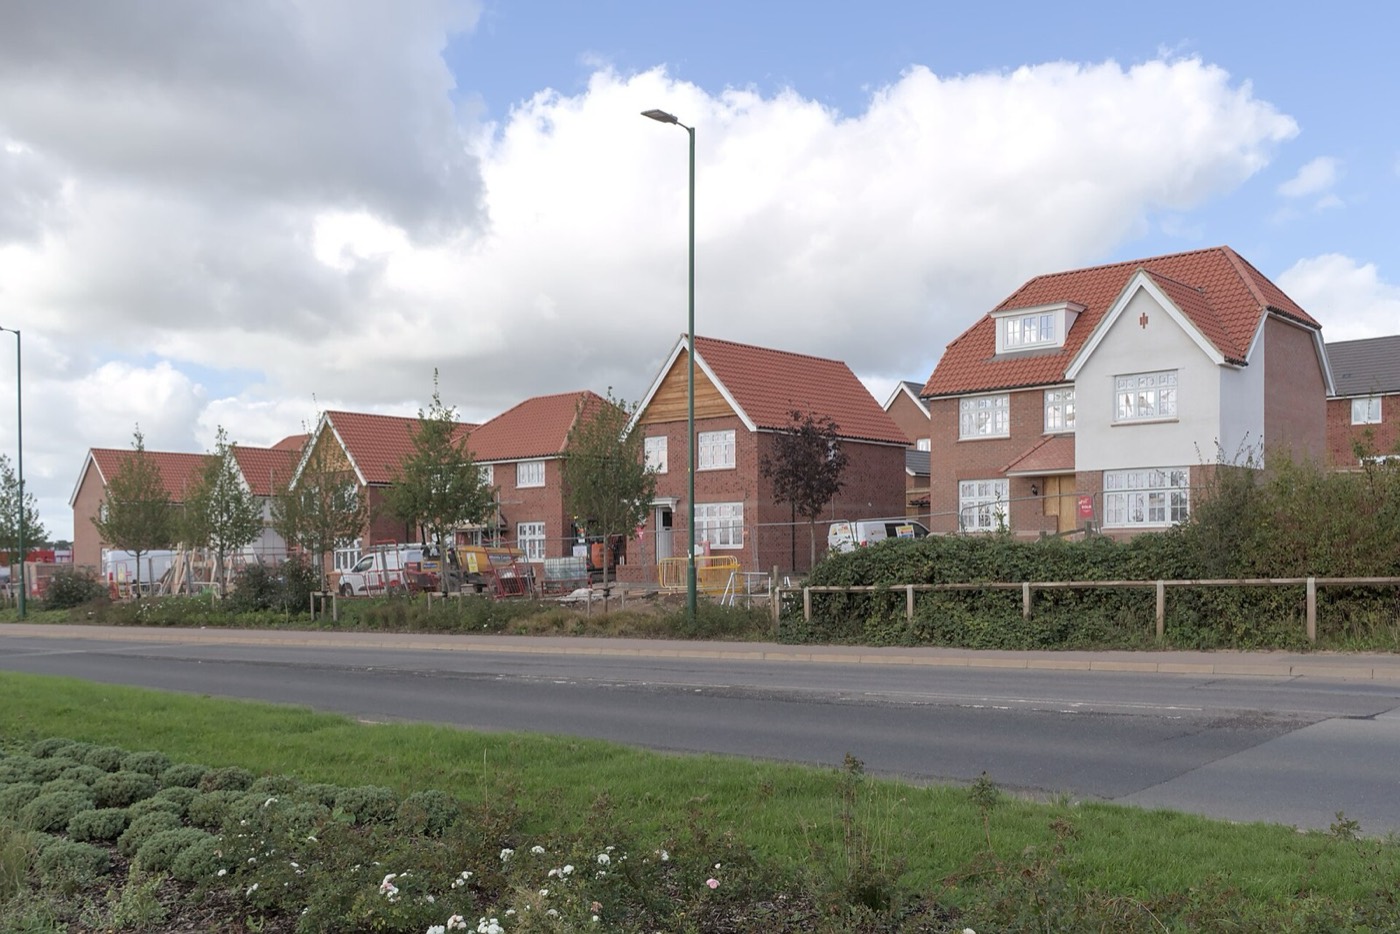
These are houses under construction at Beaumont Fold in Fairham. The photograph was taken on the seventeenth of September twenty twenty-six. It shows a physical stage of supply becoming homes, rather than a prediction of how many homes the country will build.
The existing housing stock means all the homes already there. Homes listed for sale are a much smaller and changing selection from that stock. More owners can list their properties without adding a single dwelling. That can still give buyers more choice in the short run.
England gained two hundred and eight thousand six hundred net additional dwellings in the financial year ending in twenty twenty-five. That was six per cent fewer than the preceding year. Net additions include conversions and changes of use, with demolitions subtracted. The estimate is provisional. These are not simply new builds, and this is not a UK total.
The official release puts those additions at about zero point eight one per cent of the previous stock. Even a substantial flow is small beside the accumulated homes. That is why new supply can ease pressure over time while the immediate market still depends heavily on existing homes changing hands.
5. What supports a sale price?
An asking price is an invitation. A completed sale price is an agreement backed by money. The gap between them is where the local market works. Buyers compare alternatives, sellers decide whether to wait, and lenders decide whether the proposed borrowing fits their rules.
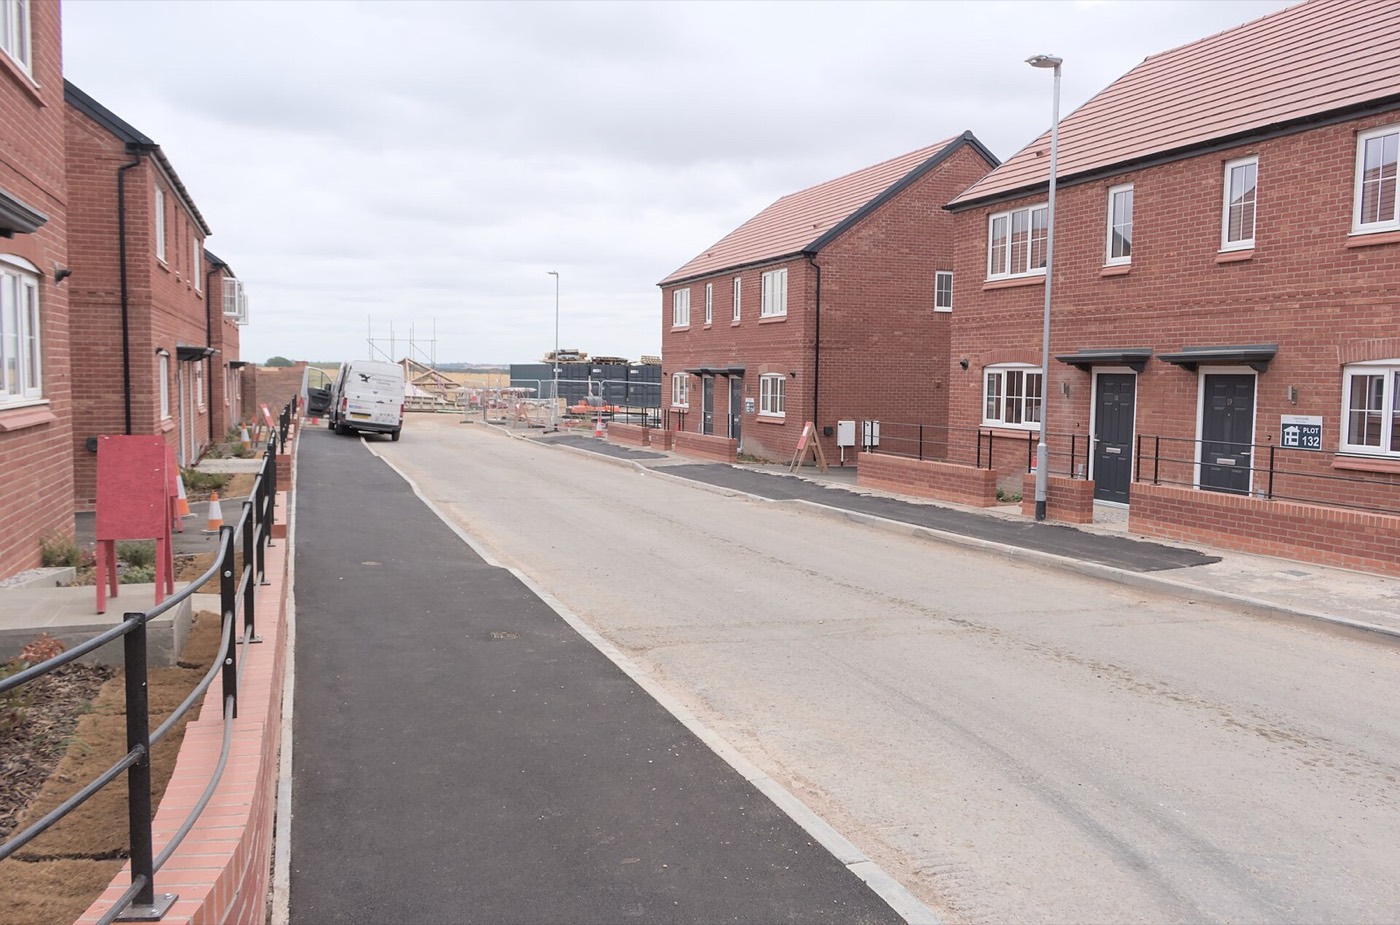
Brandshill Drive in Fairham is an example of a suburban housing street. This photograph dates from the seventeenth of August twenty twenty-six. Similar-looking homes can still differ in condition, running costs and location within the neighbourhood. A photograph cannot establish their market value.
Suppose a household wants to move but has only a modest deposit. A higher valuation may make its existing home look more valuable. It can also make the next home more expensive. Rising prices therefore do not create the same benefit for a first-time buyer, a mover and someone selling without buying again.
Income supports the monthly payment, while savings support the deposit. A mortgage supplies the remaining purchase money, subject to the lender’s checks. Together these set a buyer’s budget. The budget is a ceiling on the bid, even when the buyer loves the house.
The lender may consider other debts, regular expenses and the resilience of payments if circumstances change. Its valuation can also limit what it will lend against this particular home. Credit is the ability to borrow, not just a desire to borrow. Lending conditions can change even before a household’s salary does.
More competing listings give buyers alternatives. Fewer listings can leave sellers with stronger bargaining positions. Confidence affects whether either side acts now or waits. These are influences on negotiation, not a formula for the correct price.
A local price emerges from buyers who can pay and sellers who will accept. Employment and wages matter, but so do deposits, mortgage availability and competing properties. Interest rates enter this picture through the payment a loan requires. We can make that connection visible without guessing the next house price.
6. Rates change the monthly payment
A mortgage is a loan secured against a property. On a repayment mortgage, each payment covers interest and pays down some of the amount borrowed. That outstanding amount is the principal. The interest rate changes how much it costs to clear the loan over the agreed term.
Take an illustrative repayment loan of two hundred and forty thousand pounds over twenty-five years. At three per cent interest, the monthly payment is about eleven hundred and thirty-eight pounds. At six per cent, it is about fifteen hundred and forty-six pounds. The loan and term are unchanged; fees are excluded.
The extra payment comes from the cost of borrowing, not from an extra room or an improved kitchen. These examples assume a constant rate over the whole calculation and monthly payments. Real offers include their own fees and conditions, and a borrower’s rate can change over time.
A fixed-rate deal keeps its interest rate for the agreed fixed period. When that period ends, a new deal or the lender’s follow-on rate can change the payment. A tracker follows a specified reference rate under its contract. A variable rate can change under the lender’s terms.
That timing spreads the effect. A household protected by an existing fixed deal does not receive the same immediate shock as someone arranging a new loan. When the fixed deal expires, the remaining balance and remaining term matter. Our full-term illustration is not a personalised remortgage calculation.
On the seventeenth of September twenty twenty-six, the Bank of England held Bank Rate at three point seven five per cent. Bank Rate is the central bank’s policy rate. It is not the mortgage rate offered to every household.
Mortgage pricing also reflects lenders’ funding costs, expectations about future rates, risk and competition. A fixed mortgage offer can change before a policy announcement because expectations have already moved. The useful link is between borrowing costs and payments, not a rule that every mortgage changes by exactly the Bank Rate move.
7. Budgets shrink before prices move
Now reverse the calculation. Instead of asking what a loan costs each month, ask how much loan the same monthly budget can support. The household has not become less interested in the home. It has become less able to fund the bid that would secure it.
Keep the monthly budget at roughly eleven hundred and thirty-eight pounds. Use six per cent interest over twenty-five years. The budget supports about one hundred and seventy-six thousand six hundred pounds of borrowing. At three per cent, the original calculation supported two hundred and forty thousand pounds. This is arithmetic, not a lending offer.
An unchanged deposit would soften the reduction in the total purchase budget, but would not remove it. Other buyers might bring larger deposits or buy with cash. A market is a mixture of those positions. That is why the reduction in an example loan cannot be read as a predicted percentage fall in house prices.
Higher borrowing costs mean larger payments for a given loan. Larger payments can reduce affordable loan sizes. Smaller budgets can reduce bids or keep buyers out of the market. The pressure reaches funded housing demand through that chain.
Sellers may initially resist. A homeowner who does not need to move can withdraw a listing or wait. A buyer may also wait rather than accept a smaller home. Fewer agreements can therefore appear before a large change in recorded prices. The price statistics describe the homes that actually transact.
Lower rates can work through the same chain in the opposite direction. A given payment can support more borrowing, which can support demand. But wages, employment, supply and confidence still matter. Easier borrowing does not guarantee that prices rise everywhere.
Nor does it guarantee lasting affordability. If many buyers gain larger budgets while available homes remain scarce, part of the benefit can be absorbed in higher bids. The monthly payment and the purchase price interact. A rate change is a powerful influence, but it is not the entire housing market.
8. Joe’s 5% gross yield
Return to Joe’s example. The property is worth three hundred thousand pounds and produces fifteen thousand pounds of annual rent. A rental yield is annual rental income expressed as a percentage of a property’s price or value. Always ask which income and which value the calculation uses.
Divide fifteen thousand pounds of annual rent by three hundred thousand pounds of property value. Multiply the result by a hundred to express it as a percentage. The gross rental yield is five per cent. Gross means before the costs are taken away.
That is a useful starting comparison, but it is not a promise about money in the owner’s pocket. The value is not necessarily what an owner originally paid. Purchase costs may also belong in a calculation based on the total money invested. Different denominators answer different questions.
Operating yield removes the assumed running costs before comparing income with property value. Financed cash flow also accounts for borrowing payments. Total return includes the change in the property’s value as well as income, with the relevant costs allowed for. These are different measures.
Borrowing makes the distinction sharper. The owner’s own money may be only part of the purchase price. A return measured against that equity can behave very differently from a yield measured against the whole property. Equity means the property value left after the outstanding loan is deducted.
Rent is income from use of the home. A capital gain is a rise in the value of the asset. A valuation increase does not itself pay a bill, and a capital loss can offset rental income. Keep the income and the value change separate until calculating total return.
A fall in the property value can even raise the quoted gross yield if rent stays unchanged. That does not mean the owner has become wealthier. The percentage rose because its denominator fell. A yield should therefore lead to questions about costs, risk and valuation, rather than end the investigation.
9. What the landlord actually keeps
The tenant’s payment reaches a property with bills attached. Maintenance keeps it usable. Insurance covers specified risks. Letting or management services can cost money. Between tenants, rent may stop while some bills continue. A gross annual rent assumes income that must actually be collected.
In this illustration, fifteen thousand pounds of rent meets three thousand pounds of operating costs. That leaves twelve thousand pounds before borrowing, tax and major repairs. Against the property’s value, the operating yield is four per cent. The costs are assumptions, not a market average.
Here the operating allowance represents ordinary maintenance, insurance, agent fees and vacancy losses together. Actual accounts should show those separately. An expensive roof or boiler replacement can arrive in a single year. Averaging a repair allowance does not make the cash bill arrive smoothly.
Now assume nine thousand pounds of annual mortgage interest. Subtracting it leaves three thousand pounds before tax and major repairs. That is only one per cent of the property value. It is a simplified cash calculation, not the owner’s final taxable profit.
Tax depends on circumstances and the applicable rules. A cost paid in cash is not automatically deductible in the way an owner expects. This example deliberately does not assign a tax bill or an after-tax percentage. Transaction costs and major repairs still have to be considered too.
Interest pays for borrowing. Principal repayment reduces the debt. Both use cash, but only the principal reduction builds the owner’s equity through a smaller loan balance. Cash available to spend and economic profit are therefore not identical.
An interest-only loan pays no principal through its regular interest payments, so repayment of the borrowed amount still needs a plan. Selling may help, but the eventual sale price is uncertain. The rent account, the loan account and the property valuation must all be examined together before calling the investment profitable.
10. Can landlords simply raise rents?
A landlord with higher borrowing costs has several possible responses. They can accept less income after costs, seek a higher rent where allowed, or sell. Some own without a mortgage and do not face this particular interest bill. Others are protected temporarily by an existing fixed deal.
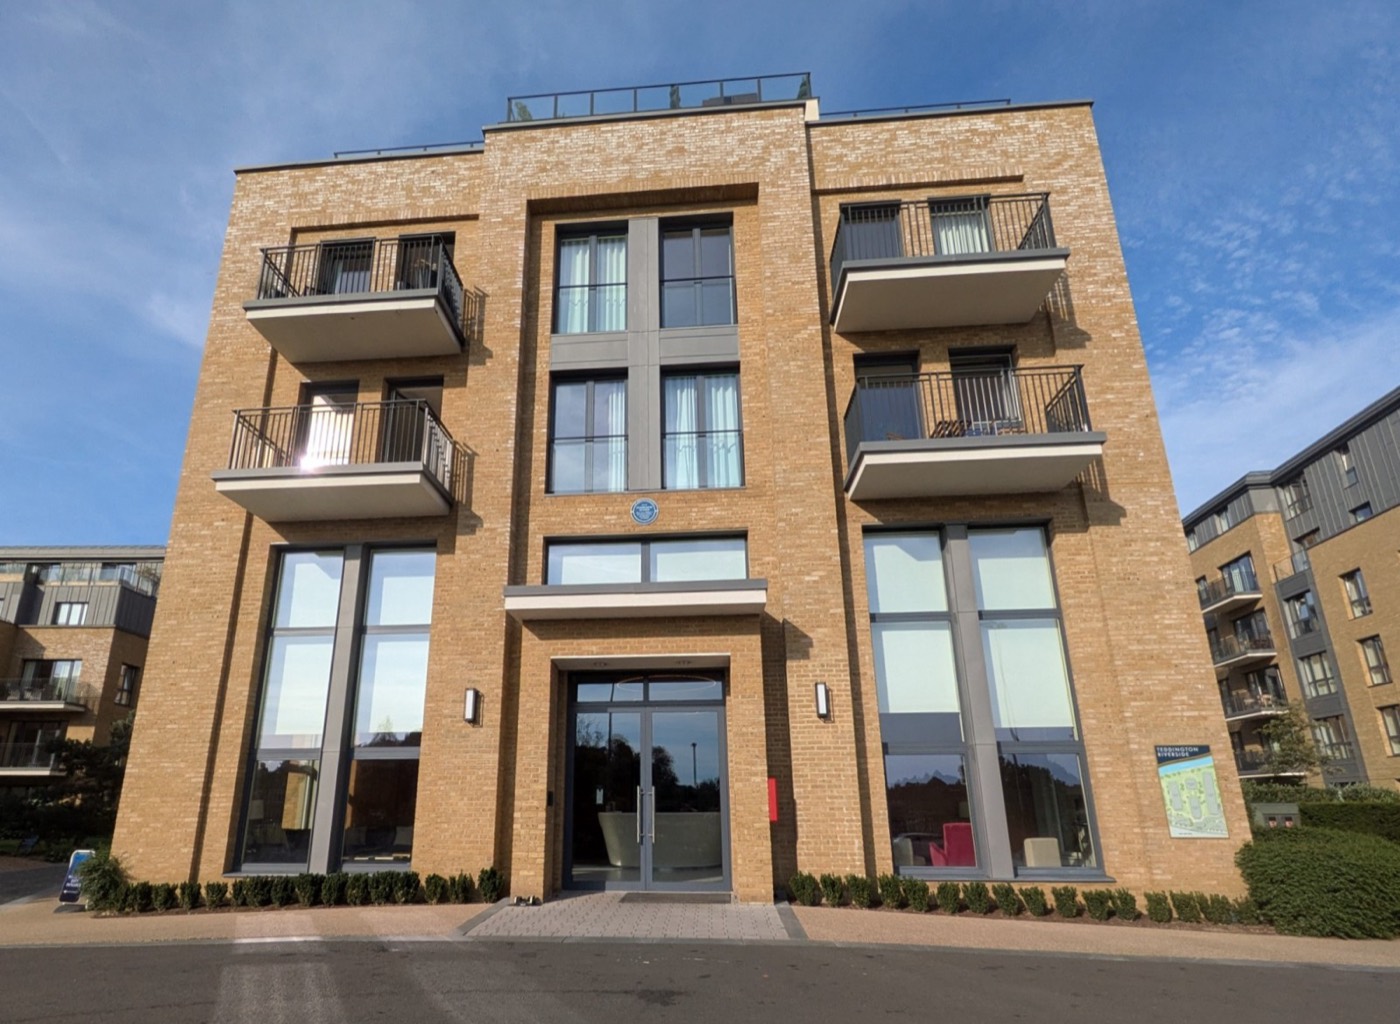
These are London flats on Broom Road in Teddington, photographed in September twenty twenty-five. They locate the discussion in a real rental market. The photograph does not identify the owners’ mortgages or tell us what any individual tenant pays.
A landlord’s desired rent is only one side of an agreement. A tenant must be able and willing to pay, and may have other homes to choose from. If those alternatives are scarce, the tenant has less room to move. If the proposed rent leaves the home empty, the landlord loses income too.
A higher borrowing bill can lead to absorbing the cost, seeking a permitted rent rise, or selling. Those are branches, not an automatic pass-through to tenants. Local rental supply and tenant incomes constrain what the market will support.
Selling does not normally destroy the building. A sale to another landlord may preserve the rental home. A sale to someone who will live there can move it from renting to owner occupation. The rental supply changes, but the total housing stock does not disappear with the old landlord.
London is in England, while Scotland, Wales and Northern Ireland have their own housing rules. This map locates the different national contexts. The rent procedure we explain next applies to covered tenancies in England, rather than the entire UK.
That distinction is essential when reading a national housing headline alongside a rule about an individual tenancy. The geography of the statistic and the geography of the law need to be checked separately.
England’s rules changed from the first of May twenty twenty-six for covered private tenancies. Rent increases are limited to once yearly and cannot occur in the first twelve months of a new tenancy. The landlord must use the required form and give at least two months’ notice.
Government guidance also says tenants can challenge a proposed increase above market rent. This is an England explanation, not a statement of rules across the whole UK. Legal procedure and market affordability operate together. A landlord’s mortgage cost alone establishes neither the lawful increase nor the rent a tenant can sustain.
11. Property is not guaranteed
A home is useful, tangible and expensive to move out of an investment account. Buying and selling involve legal work, possible transaction taxes and other fees. A buyer needs time to inspect and finance it. The owner cannot assume a quick sale at the last advertised value.
Dovecote Grange in Fairham shows ordinary suburban England homes in September twenty twenty-six. A solid-looking building still needs maintenance, and its resale price remains uncertain. Physical permanence does not guarantee financial performance.
Holding much of your wealth in one property also concentrates risk. A defect in that building, the loss of a tenant or weaker demand in that area can matter greatly to its owner. Borrowing adds a payment obligation that continues even when income falls. Regulation can change the costs and duties of ownership.
Consider repairs, vacancy, borrowing costs and selling costs together. Add the difficulty of selling quickly and the concentration in a single asset. These risks do not prove that property must lose money. They explain why its returns cannot be guaranteed.
For an owner-occupier, the home also supplies somewhere to live. That benefit belongs beside the financial calculation, without being confused with rental income that the household never receives. A landlord has a different purpose and a different cash account. The same building can therefore play different roles for different owners.
The central chain remains simple. Higher mortgage rates can weaken affordability, reducing buyer budgets and funded demand. Rents depend on tenant incomes and available rental homes, while rental profitability depends on costs as well as receipts. Each link needs its own evidence.
That is the framework to take away from this video. Ask what is happening to incomes, borrowing and the supply of suitable homes. Then ask which price or return the headline actually measures. A five per cent gross yield starts an investigation. It does not finish one, and it cannot make property a guaranteed investment.
Sources and credits
Photo credits (Wikimedia Commons)
- Housing construction at Beaumont Fold, Fairham, England — 17 September 2026: Aethonatic, CC0 - https://commons.wikimedia.org/wiki/File%3AUnder_construction_houses_at_Beaumont_Fold_%281%29_-_17_September_2026.jpg
- Suburban housing street, Brandshill Drive, Fairham, England — 17 August 2026: Aethonatic, CC0 - https://commons.wikimedia.org/wiki/File%3ABrandshill_Drive%2C_Fairham_%281%29_-_17_August_2026.jpg
- Suburban England homes, Dovecote Grange, Fairham — 17 September 2026: Aethonatic, CC0 - https://commons.wikimedia.org/wiki/File%3ADovecote_Grange%2C_Fairham_-_17_September_2026.jpg
- London flats, Broom Road, Teddington — 6 September 2025: Hsq7278, CC0 - https://commons.wikimedia.org/wiki/File%3ASite_of_former_Teddington_Studios%2C_London.png


Primary sources
- https://www.ons.gov.uk/economy/inflationandpriceindices/bulletins/privaterentandhousepricesuk/september2026.
- https://www.nationwide.co.uk/media/hpi/reports/annual-house-price-growth-halves-in-september.
- https://www.nationwide.co.uk/media/hpi.
- https://www.bankofengland.co.uk/explainers/how-does-the-housing-market-affect-the-economy.
- https://www.bankofengland.co.uk/financial-stability-report/2022/december-2022.
- https://www.gov.uk/government/statistics/housing-supply-net-additional-dwellings-england-2024-to-2025/housing-supply-net-additional-dwellings-england-2024-to-2025.
- https://www.bankofengland.co.uk/-/media/boe/files/quarterly-bulletin/2008/understanding-dwellings-investment.
- https://www.bankofengland.co.uk/monetary-policy-summary-and-minutes/2026/september-2026.
- https://www.moneyhelper.org.uk/en/blog/buy-or-rent-a-home/how-will-interest-rates-affect-my-mortgage.
- https://www.moneyhelper.org.uk/en/blog/buy-or-rent-a-home/buy-to-let-mortgages-explained.
- https://www.bankofengland.co.uk/quarterly-bulletin/2023/2023/the-buy-to-let-sector-and-financial-stability.
- https://www.gov.uk/guidance/renters-rights-act-overview-for-tenants.
- https://github.com/joewoods1968/Video-Production-Content/issues/214.
Not regulated financial advice.